What Line Is AGI on Form 1040? Line 11a in 2025 (Line 11 Before)
On the 2025 Form 1040, AGI is line 11a (line 9 minus line 10), repeated on line 11b; on the 2024 form it was line 11. Line by line, with a worked example.
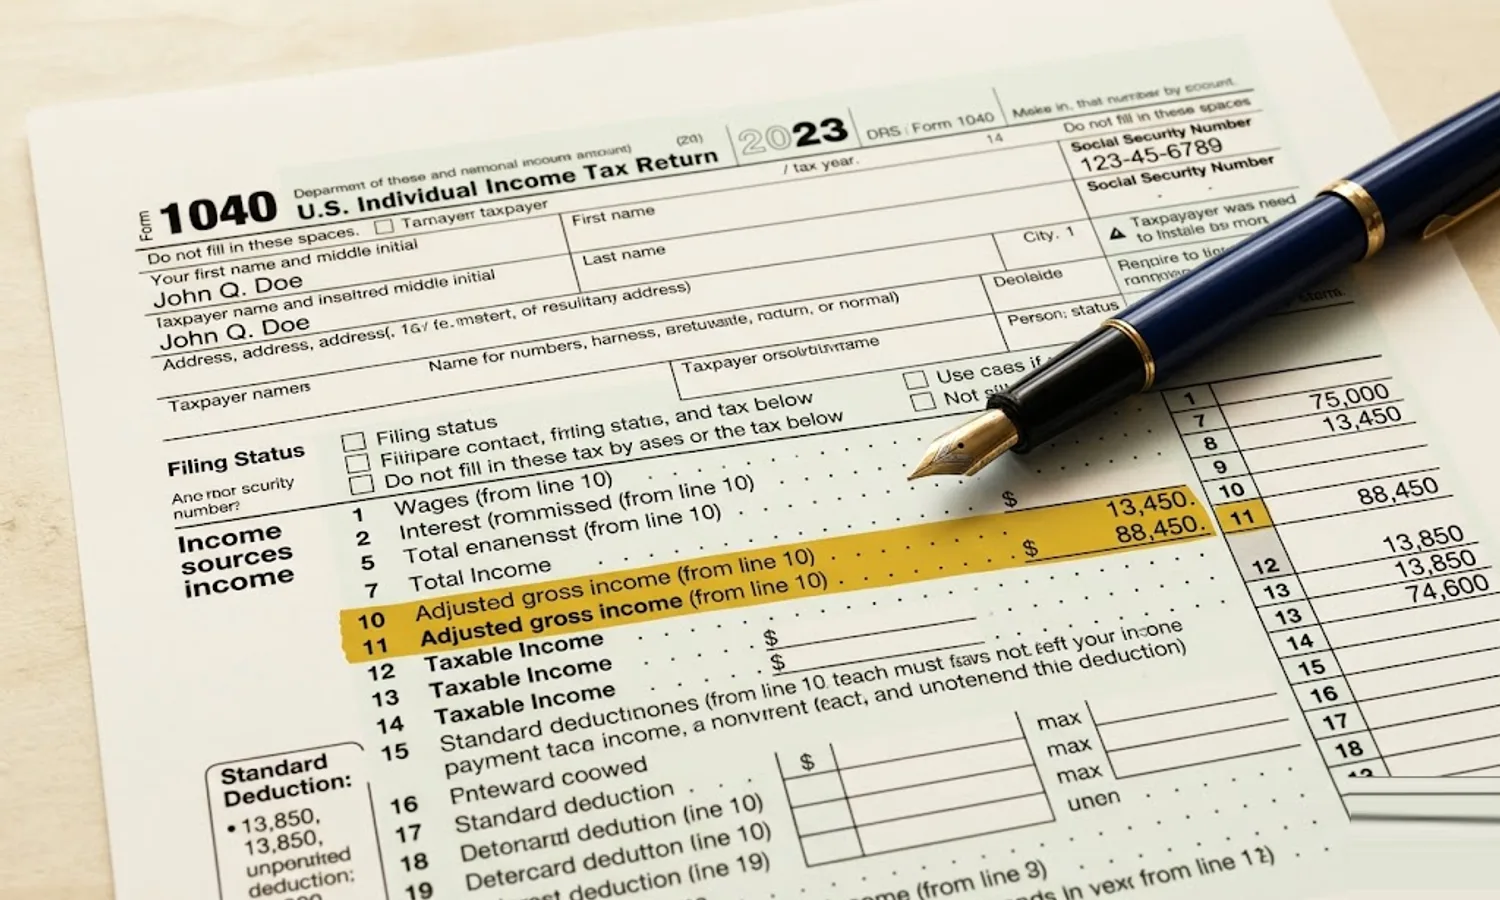
Adjusted gross income, or AGI, is your total income from all sources for the year minus a short list of statutory adjustments — and on a federal return it lands on Form 1040, line 11. It is not the same as your gross income, and it is not your taxable income; it sits between the two, and it is the number that most credit and deduction phase-outs are actually measured against.
The short answer: AGI is line 11a on the 2025 Form 1040 and line 11 on the 2024 form and earlier. It equals line 9 (total income) minus line 10 (adjustments to income, carried up from Schedule 1, line 26) — so line 11a = line 9 − line 10. The 2025 form then repeats the figure on line 11b at the top of page 2; taxable income comes later, on line 15 (line 11b minus line 14).
At a glance, here is where each number sits on the 2025 Form 1040 (the 2024 line numbers in parentheses where they differ):
| Form 1040 line | What it holds |
|---|---|
| Line 9 | Total income (the sum of lines 1z–8) |
| Line 10 | Adjustments to income (carried up from Schedule 1, line 26) |
| Line 11a (2024: line 11) | Adjusted gross income (AGI) — line 9 minus line 10 |
| Line 11b (new in 2025) | The same AGI, carried to the top of page 2 |
| Line 15 | Taxable income (line 11b minus line 14; line 11 minus line 14 in 2024) |
US federal income tax has two important “intermediate” numbers between what you earned during the year and the tax you actually owe: adjusted gross income (AGI) and taxable income. Both are computed mechanically on Form 1040 from the numbers in the boxes of your W-2s, 1099s, and brokerage statements. AGI lives on Form 1040, line 11. Taxable income lives further down on line 15. The two are not interchangeable, and the distinction matters more than most filers realize — because dozens of tax provisions, credit eligibility tests, and downstream phase-outs are keyed to AGI specifically, not to gross income, not to taxable income, not to wages.
This guide walks through how AGI is computed on Form 1040, line by line. We will cover lines 1a through 8 (the income side that builds total income on line 9), the role of Schedule 1 Part I (the “other income” line items that flow up into line 8 of Form 1040), and the role of Schedule 1 Part II (the above-the-line adjustments that get subtracted on line 10 to produce AGI on line 11). At the end we will compare AGI to gross income and to taxable income, walk through the most common phase-outs that AGI gates, and finish with verification steps for filers who want to be sure they have the right number.
Every figure on Form 1040 is annual and applies to a single tax year. The form layout described here — with AGI on line 11 — applies to tax years 2020 through 2024 (returns filed 2021 through early 2025); the 2025 form relabels the line 11a and repeats it as 11b, with the arithmetic unchanged, so the line-by-line walkthrough below fits a 2022, 2023, 2024, or 2025 Form 1040 alike. Specific line numbers, schedule references, and dollar thresholds are sourced to IRS publications and forms instructions listed at the end of the piece.
Why AGI is the hinge point of the whole return
The federal income tax form is structured around two computational “stops” on the way from gross income to tax. The first stop is AGI — line 11. The second stop is taxable income — line 15. AGI is the more important of the two for planning purposes, because the federal tax code uses AGI (or one of its close variants, MAGI) as the eligibility number for a long list of provisions that do not appear on the 1040 itself but show up as schedules and worksheets.
The Roth IRA direct-contribution capacity phases out across a specific AGI band that differs by filing status. The Premium Tax Credit for Affordable Care Act marketplace coverage is computed against a MAGI that starts from AGI. The Saver’s Credit, the American Opportunity tax credit and the Lifetime Learning Credit, the deduction for student loan interest itself, and the qualified business income deduction all phase in or out on AGI-based thresholds. Even non-tax programs — federal student aid (the FAFSA), some state programs, and certain federal benefits — pull AGI from your filed return as the income proxy.
The practical consequence is that a household two thousand dollars over the wrong AGI threshold can lose multiple thousands of dollars of credit eligibility. This is also why above-the-line adjustments (which reduce AGI directly on the Schedule 1 Part II side) are structurally more valuable than same-sized itemized deductions (which reduce taxable income from below AGI but do nothing to preserve AGI-tested eligibility). A $5,000 traditional IRA contribution that reduces AGI can preserve Roth contribution capacity, Premium Tax Credit eligibility, and several other items that a $5,000 charitable contribution on Schedule A cannot.
Understanding which line is AGI, and which adjustments move it, is therefore the foundation of any tax planning decision that interacts with credits and phase-outs.
The income side — Form 1040 lines 1a through 8, line by line
The top portion of Form 1040 — through line 9 — adds up every category of income the taxpayer is required to report. Each line corresponds to a specific source of money, and most are populated either from a third-party information return (a W-2, a 1099, a 5498) or from a schedule that itself rolls up several items.
Line 1a — Total amount from Form(s) W-2, box 1. This is the headline wage and salary number every employed taxpayer recognizes. The figure on W-2 box 1 is already net of pre-tax 401(k) contributions, pre-tax health insurance premiums, and pre-tax HSA contributions made via payroll, because those amounts were subtracted before the W-2 was issued. Most employees will see exactly the box 1 amount on line 1a. Multiple jobs in the same year produce multiple W-2s, and the line 1a entry is the sum.
Lines 1b through 1h — household-employee wages not on W-2, tip income not reported to employer, Medicaid waiver payments, taxable scholarships, prison income, and similar narrow items. These are uncommon for typical filers. Each has a specific line because each is treated slightly differently for FICA tax purposes.
Line 1z — Add lines 1a through 1h. This is the total wage-related income figure for the return. For a single-job W-2 filer with no scholarships or unusual items, line 1z equals line 1a. For filers with multiple jobs, scholarships, or tip income not previously reported to the employer, line 1z aggregates everything wage-like.
Line 2a — Tax-exempt interest. Interest from municipal bonds and similar tax-exempt sources. Reported on Form 1099-INT box 8. This figure does NOT add to AGI directly — it is reported for transparency and to feed certain MAGI calculations downstream (Premium Tax Credit MAGI, Social Security taxation thresholds), but the tax-exempt interest itself is not federal income tax.
Line 2b — Taxable interest. Interest from savings accounts, certificates of deposit, money market funds, US Treasury securities, taxable corporate bonds, and similar sources. Reported on Form 1099-INT box 1. This figure DOES add to AGI. For filers with significant HYSA balances, T-bill ladders, or taxable bond exposure, this can be a substantial line.
Line 3a — Qualified dividends. Dividends that qualify for the preferential long-term capital gains tax rate. Reported on Form 1099-DIV box 1b. This figure adds to AGI but will be taxed at the qualified-dividend rate later in the computation, not at ordinary rates.
Line 3b — Ordinary dividends. All dividends, including the qualified portion. Reported on Form 1099-DIV box 1a. Adds to AGI. The ordinary-dividend figure on line 3b is always greater than or equal to the qualified-dividend figure on line 3a, because qualified is a subset of ordinary.
Line 4a / 4b — IRA distributions: gross amount and taxable amount. Reported on Form 1099-R. Line 4a is the gross distribution from a traditional, Roth, SEP, or SIMPLE IRA. Line 4b is the taxable portion. For traditional IRA distributions with no after-tax basis, line 4b equals line 4a. For Roth distributions of contributions, line 4b is zero. For traditional IRAs with after-tax basis from Form 8606, line 4b is computed via the pro-rata rule. Line 4b is what adds to AGI; line 4a does not (it is reported for transparency).
Line 5a / 5b — Pensions and annuities: gross and taxable. Same pattern as line 4. The taxable portion on line 5b adds to AGI.
Line 6a / 6b / 6c — Social Security benefits: gross, taxable, and the “lump-sum election” indicator. Form SSA-1099 reports the gross. Whether any of it is taxable depends on a worksheet that compares your provisional income (AGI plus tax-exempt interest plus half of Social Security) against thresholds that vary by filing status and have been frozen since 1984. The taxable portion on line 6b — between 0% and 85% of the gross — is what adds to AGI. Two adjacent mechanics for recipients who have not reached full retirement age: the Social Security earnings test can withhold checks if work income exceeds the annual cap, and the gross benefit on line 6a resets every January with the COLA — the 2027 adjustment is being determined by this summer’s CPI-W readings.
Line 7 — Capital gain or (loss). Comes from Schedule D, which itself rolls up Form 8949 for individual security sales. Long-term gains and short-term gains both flow here; long-term and qualified dividends are taxed at preferential rates further down the form. If Schedule D shows a net capital loss, this line is negative (subject to the $3,000 annual ordinary-income loss limit; excess carries forward to future years).
Line 8 — Additional income from Schedule 1, line 10. This is the catch-all that brings in everything not covered by lines 1 through 7. Schedule 1 Part I includes net self-employment income from Schedule C and Schedule F, rental and royalty income from Schedule E, unemployment compensation, gambling winnings, prizes and awards, jury duty pay, alimony received (for divorce agreements executed before 2019), state and local tax refunds (if itemized in a prior year), and the long tail of less common income types. The total of Schedule 1 Part I lands on Schedule 1 line 10 and flows up to Form 1040 line 8.
Line 9 — Total income. Sum of lines 1z, 2b, 3b, 4b, 5b, 6b, 7, and 8. This is gross income for federal income tax purposes — every dollar the IRS expects to see, before any adjustments.
The adjustments side — Schedule 1 Part II, adjustment by adjustment
Form 1040 line 10 is a single number: “Adjustments to income from Schedule 1, line 26.” But that single number contains the entire above-the-line deduction strategy, and understanding what is in it is where most planning leverage lives.
Schedule 1 Part II runs from line 11 through line 26. Each line is a specific statutory adjustment to gross income. The total on line 26 is the figure that gets subtracted on Form 1040 line 10 to produce AGI on line 11.
Schedule 1 line 11 — Educator expenses. For 2026 the cap is $350 per eligible educator (K-12 teacher, counselor, principal, aide), or $700 on a joint return where both spouses qualify. The figure is indexed for inflation and rose from $300 under Rev. Proc. 2025-32, section 3.12. The classroom supply receipt drawer that teachers maintain throughout the year is what this line pays back.
Schedule 1 line 12 — Certain business expenses of reservists, performing artists, and fee-basis government officials. Narrow category, populated by Form 2106.
Schedule 1 line 13 — Health savings account (HSA) deduction. From Form 8889. Reduces AGI by the amount the filer contributed to an HSA outside of payroll. Contributions made via payroll are already excluded from W-2 box 1 and do not go here — only “out-of-pocket” HSA contributions that the filer wrote a check for or transferred from a bank account.
Schedule 1 line 14 — Moving expenses for members of the Armed Forces. From Form 3903. Limited to active-duty military with a permanent change of station after the Tax Cuts and Jobs Act eliminated the moving deduction for everyone else.
Schedule 1 line 15 — Deductible part of self-employment tax. The “half of SE tax” deduction. Self-employed filers compute their full 15.3% SE tax on Schedule SE; half of that figure is deductible above the line on this Schedule 1 line. This is one of the largest above-the-line adjustments for typical self-employed filers — a $100,000 net Schedule C profit produces roughly $14,000 of SE tax, of which $7,000 is deductible here.
Schedule 1 line 16 — Self-employed SEP, SIMPLE, and qualified plans. Solo 401(k), SEP-IRA, SIMPLE-IRA contributions for self-employed filers. Computed on a separate IRS worksheet. Can be substantial — a high-earning solo consultant may deduct $50,000+ on this line via a solo 401(k) employer contribution plus profit-sharing.
Schedule 1 line 17 — Self-employed health insurance deduction. The premiums a self-employed filer paid for medical, dental, and qualified long-term care coverage for themselves, spouse, and dependents. Capped at net SE income.
Schedule 1 line 18 — Penalty on early withdrawal of savings. The CD or savings bond early-withdrawal penalty reported on 1099-INT box 2. Reduces AGI by the penalty amount, partially offsetting the lost interest.
Schedule 1 line 19a / 19b / 19c — Alimony paid. Only for divorce or separation agreements executed before January 1, 2019. The Tax Cuts and Jobs Act eliminated the alimony deduction for agreements signed in 2019 or later; those alimony payments are now nondeductible to the payer and nontaxable to the recipient.
Schedule 1 line 20 — IRA deduction. Traditional IRA contributions for the year, subject to the deduction phase-out if the filer (or spouse) is covered by an employer retirement plan. A non-covered filer can deduct the full annual limit regardless of income — for 2026 that is $7,500, or $8,600 from age 50, because the IRA catch-up rose to $1,100 under Notice 2025-67. A covered filer phases out across a specific AGI band.
Schedule 1 line 21 — Student loan interest deduction. Up to $2,500 of interest paid on qualified student loans, phased out for 2026 across a modified-AGI band that runs from $85,000 to $100,000 for single filers and from $175,000 to $205,000 on a joint return (Rev. Proc. 2025-32, section 3.29). Reported on Form 1098-E.
Schedule 1 line 22 — Reserved for future use. Was used for tuition and fees deduction in prior years; that provision has expired.
Schedule 1 line 23 — Archer MSA deduction. Very narrow, mostly historical. Replaced by HSA for most filers.
Schedule 1 line 24a–24z — Other adjustments. Long-tail items: jury duty pay turned over to employer, reforestation amortization, deductible attorney fees and court costs for discrimination suits, repayment of supplemental unemployment benefits, contributions to section 501(c)(18)(D) pension plans, etc. Each is its own narrow case.
Schedule 1 line 25 — Total other adjustments (sum of lines 24a–24z).
Schedule 1 line 26 — Add lines 11 through 23 and 25. This is the figure that flows up to Form 1040 line 10 and gets subtracted from total income on line 9 to produce AGI on line 11.
A worked AGI example on Form 1040, line by line
Consider a filer with the following income picture for tax year 2025:
- W-2 box 1 wages: $90,000
- HYSA interest (1099-INT box 1): $1,800
- Brokerage ordinary dividends: $1,200 (of which $1,100 qualified)
- Long-term capital gain on a stock sale: $4,000
- Side consulting Schedule C net profit: $20,000
Above-the-line adjustments:
- Deductible half of SE tax on the consulting income (Schedule SE produces $2,826 of SE tax; half is $1,413)
- Traditional IRA contribution: $7,000 (filer is not covered by a workplace plan, so fully deductible)
- Student loan interest paid: $1,800
Walking through Form 1040:
- Line 1a / 1z: $90,000
- Line 2b: $1,800
- Line 3a: $1,100 (informational; the $1,100 is also inside line 3b)
- Line 3b: $1,200
- Line 7: $4,000
- Line 8: $20,000 (from Schedule 1 line 10, which has Schedule C net profit of $20,000)
- Line 9 (total income): $90,000 + $1,800 + $1,200 + $4,000 + $20,000 = $117,000
Schedule 1 Part II:
- Line 15: $1,413 (deductible SE tax)
- Line 20: $7,000 (IRA contribution)
- Line 21: $1,800 (student loan interest, under the $2,500 cap and below the phase-out)
- Line 26: $1,413 + $7,000 + $1,800 = $10,213
Form 1040 line 10: $10,213. Line 11 (AGI): $117,000 − $10,213 = $106,787.
This is the figure that downstream phase-outs, state returns, and prior-year identity verification will reference. From here, the filer subtracts the standard deduction for their filing status and year, and the QBI deduction (20% of Schedule C net profit, with limitations), on Form 1040 lines 12 and 13 to arrive at taxable income on line 15. Tax is then computed on taxable income, but every credit eligibility test for the year — Roth contribution capacity, Saver’s Credit, education credits — looks back at the AGI of $106,787.
Example two: a single W-2 and nothing else
Most returns are far simpler than the one above, and the simple case is worth showing explicitly because it surprises people. Take a filer whose entire year is one job: W-2 box 1 wages of $62,000, no interest, no side income, no adjustments to report on Schedule 1.
- Line 1z: $62,000
- Line 9 (total income): $62,000
- Line 10 (adjustments): $0
- Line 11 (AGI): $62,000
When there are no above-the-line adjustments, line 11 equals line 9, and AGI equals box 1 of the W-2 exactly. There is no calculation to perform. If you are looking for your AGI and your tax situation looks like this one, the number is already printed on your W-2 — a point covered in more depth in our guide to finding AGI from a W-2.
Example three: where retirement contributions do and do not appear
This is the case that produces the most errors, because three retirement accounts that feel similar are treated in three different ways.
Consider a filer with $85,000 in gross salary who contributed $10,000 to a traditional 401(k) through payroll, $4,000 to an HSA directly with the custodian (not through payroll), and $7,000 to a deductible traditional IRA.
- The 401(k) contribution never appears on Form 1040 at all. It was already excluded from W-2 box 1 by the employer, so box 1 reads $75,000, not $85,000. Deducting it again on Schedule 1 would be double-counting — a common and costly error.
- The HSA contribution made outside payroll is an adjustment, reported on Schedule 1 line 13 via Form 8889. Had it been made through payroll, it would already be excluded from box 1 like the 401(k), and claiming it again would be the same double-count.
- The deductible IRA contribution is an adjustment, on Schedule 1 line 20.
Walking it through: line 1z is $75,000 (box 1, already net of the 401(k)). Line 9 is $75,000. Schedule 1 line 26 totals $4,000 + $7,000 = $11,000, which carries to line 10. Line 11 (AGI) is $64,000.
The rule underneath all three cases: an adjustment belongs on Schedule 1 only if the money has not already been removed from W-2 box 1. Anything your employer excluded before printing the W-2 is spent; claiming it a second time inflates your refund and is exactly the sort of arithmetic the IRS matches automatically against the W-2 your employer filed.
How to calculate your AGI from a W-2 (the simple case)
The worked example above had a freelancer with self-employment income and adjustments, which is the hard case. The far more common case is a single-job employee with a W-2 and little else, and for that filer the calculation is short — but it hides the single most common AGI error, so it is worth walking slowly.
Start with the figure that trips people up. Your AGI is not printed anywhere on your W-2, because AGI only exists once income from all of your forms is summed on Form 1040 — the W-2 reports one job’s wages, not your whole return. The number to start from is Box 1 of the W-2, labeled “Wages, tips, other compensation.” The crucial point is that Box 1 is already reduced by your pre-tax payroll deductions: pre-tax 401(k) contributions, pre-tax health-insurance premiums, and payroll health savings account contributions are all subtracted before Box 1 is printed. That is exactly why Box 1 is usually smaller than Box 3 (Social Security wages) and Box 5 (Medicare wages). The most common mistake is subtracting those pre-tax items again on the way to AGI — they are already gone, and double-counting them understates AGI.
For a single filer with one job, $62,000 in Box 1, and $400 of taxable interest from a high-yield savings account reported on a 1099-INT, with no above-the-line adjustments, the build to AGI is short:
| Step | Source | Amount |
|---|---|---|
| Wages (already net of pre-tax 401(k), health, and HSA) | W-2 Box 1 | $62,000 |
| + Taxable interest | 1099-INT Box 1 | $400 |
| = Total income | Form 1040 line 9 | $62,400 |
| − Above-the-line adjustments | Schedule 1 line 26 | $0 |
| = Adjusted gross income | Form 1040 line 11 | $62,400 |
So this filer’s AGI is $62,400 — Box 1 plus the interest, with nothing subtracted. Now add one adjustment: suppose the same filer makes a $3,000 deductible contribution to a traditional IRA. That contribution is an above-the-line adjustment on Schedule 1, so it lowers total income by $3,000 and the AGI falls to $59,400. That is the whole mechanism by which a pre-tax retirement contribution lowers AGI — and, with it, opens or preserves the AGI-keyed phase-outs covered later in this guide. The takeaway for the one-job filer: take Box 1, add any interest, dividends, or other income from your 1099s, subtract any Schedule 1 adjustments, and the result is your AGI — your W-2 alone does not show it. For the W-2-specific walkthrough — why Box 1 is not your AGI and how to rebuild the number from it — see Your W-2 doesn’t show your AGI.
AGI vs gross income vs taxable income
The three numbers are related but not interchangeable, and using the wrong one is one of the most common errors in tax planning conversations.
Gross income is everything earned during the year, before any subtractions. For the filer above, gross income is approximately $117,000 (Form 1040 line 9). This is the broadest measure.
Adjusted gross income (AGI) is gross income minus the Schedule 1 Part II above-the-line adjustments. For the filer above, AGI is $106,787 (Form 1040 line 11). This is the figure that drives most phase-outs and downstream eligibility.
Modified AGI (MAGI) is AGI with specific add-backs that vary by tax provision — and because the difference is where most eligibility mistakes happen, it gets its own comparison in the next section.
Taxable income is AGI minus the standard deduction or itemized deductions (whichever is greater), minus the qualified business income deduction. For the filer above, taxable income is approximately $106,787 − $16,100 (the single standard deduction for 2026) − $4,000 = $86,687 on line 15. This is the figure to which the tax brackets are applied to compute the actual income tax.
The key planning insight: AGI is the lever for credit and deduction phase-outs. Above-the-line adjustments (Schedule 1 Part II) reduce AGI and therefore preserve eligibility. Below-the-line deductions (standard or Schedule A) reduce taxable income but do nothing for AGI-tested phase-outs. When a household near a phase-out threshold can choose between a contribution that adjusts AGI and a deduction that does not, the AGI adjustment is almost always more valuable.
AGI vs MAGI
AGI and MAGI are not the same number, and the gap between them is where most eligibility mistakes happen. AGI is the figure on Form 1040, line 11. MAGI — modified adjusted gross income — is AGI with a set of add-backs that changes depending on which provision you are testing.
| AGI | MAGI | |
|---|---|---|
| Where it lives | Form 1040, line 11 | Nowhere on the form — recomputed per provision |
| How it is built | Total income minus Schedule 1 adjustments | AGI plus provision-specific add-backs |
| What it gates | State returns, prior-year e-file verification | Roth IRA capacity, Premium Tax Credit, NIIT, IRMAA, IRA deduction |
There is no single MAGI. The Roth IRA MAGI adds back the IRA deduction, the student loan interest deduction, and the foreign earned income exclusion; the Premium Tax Credit MAGI adds back tax-exempt interest and untaxed Social Security; the Net Investment Income Tax MAGI adds back the foreign earned income exclusion. Each provision defines its own. The full set of formulas is in the MAGI explainer and the MAGI glossary entry.
What AGI gates — the phase-outs you should know
The phase-out provisions tied to AGI or MAGI fill a long appendix of the federal tax code. The most consequential for typical filers:
- Roth IRA contribution capacity. Phases out across a band that depends on filing status. Tested against Roth-specific MAGI, which is close to AGI for filers without IRA deductions, student loan interest, or foreign income.
- Traditional IRA deduction capacity. Phases out for filers covered by an employer retirement plan, across a separate AGI band.
- Premium Tax Credit (ACA marketplace coverage subsidy). Phases out based on Premium Tax Credit MAGI relative to the federal poverty level for the household size.
- Saver’s Credit. Available only below specific AGI thresholds — a refundable-for-low-income credit on retirement contributions.
- American Opportunity Tax Credit and Lifetime Learning Credit. Both phase out across AGI bands. The American Opportunity Credit is partially refundable; the Lifetime Learning Credit is nonrefundable.
- Student loan interest deduction itself. Phases out across an AGI band — the same deduction that reduces AGI is itself capped by an AGI threshold above.
- Qualified business income (QBI) deduction. For specified service trades and businesses, the 20% deduction phases out across AGI bands.
- Passive activity loss deductibility. Special $25,000 allowance for rental real estate losses phases out at AGI between $100,000 and $150,000.
- Net Investment Income Tax (NIIT). 3.8% surtax on investment income kicks in above NIIT-MAGI thresholds.
- Additional Medicare Tax. 0.9% surtax on wages and SE income above filing-status thresholds.
For a household near any of these thresholds, the planning move is to identify whether an above-the-line adjustment — a larger traditional IRA contribution, an HSA contribution, a solo 401(k) contribution for a self-employed filer — can pull AGI back under the threshold and unlock the affected credit or deduction. This is the canonical use case for understanding AGI as a distinct number.
Common errors and how to verify
Filers tend to make a handful of recurring errors when working with AGI:
Confusing AGI with taxable income. Pulling taxable income (line 15) from a prior return when the e-filing flow asks for AGI (line 11) will fail the identity verification. The fix is to always pull AGI from line 11 specifically.
Confusing AGI with W-2 box 1 wages. Wages are only one component of AGI. A filer with substantial interest, dividends, or capital gains will have AGI considerably higher than W-2 box 1.
Using one MAGI for all provisions. MAGI for Roth IRA purposes is not the same as MAGI for Premium Tax Credit purposes. Each provision defines its own MAGI; using the wrong one produces eligibility errors that the IRS catches later via Form 1095-A reconciliation or Form 5498 cross-checks.
Missing Schedule 1 Part II adjustments. Filers who use tax software typically have these prompted; filers using paper forms or simplified online forms sometimes miss the HSA deduction, the educator expense deduction, or the half-of-SE-tax deduction. Each missed item leaves AGI artificially high and may forfeit other benefits.
Forgetting the student loan interest deduction phase-out. The deduction itself reduces AGI, but the deduction is itself capped by an AGI threshold above which it phases out. Filers near the phase-out should verify the calculated deduction matches Form 1098-E box 1 capped by the phase-out math, not just the gross interest paid.
The verification steps for a filer who wants to be sure their AGI is right:
- Pull line 11 from the most recent filed Form 1040. Save a digital copy each year for this purpose.
- Cross-check against the IRS account transcript. Free at irs.gov/individuals/get-transcript. The Tax Return Transcript shows line-by-line figures including AGI.
- Compare to any state return. Most state income tax forms start from federal AGI; the figure on the state form should match the federal line 11.
- Recompute Schedule 1 Part II by hand if any phase-out outcome depends on the AGI figure. The mechanical addition is short and removes any tax-software shortcut errors.
The mechanics of AGI computation are stable year over year. What changes annually: the specific dollar thresholds for phase-outs (indexed for inflation), the standard deduction amount, and occasional new above-the-line adjustments added by Congress. The line numbers — line 11 for AGI, Schedule 1 line 26 for the total adjustments — have held for every tax year from 2020 through 2025. Two earlier layouts differ and trip up anyone pulling an older return: the 2019 Form 1040 placed AGI on line 8b, and the 2018 “postcard” redesign placed it on line 7.
What this guide does not cover
This guide focused on AGI computation on Form 1040 for a typical individual filer. It does not cover:
- Filing status mechanics in detail. The choice between single, head of household, married filing jointly, and married filing separately is its own topic and changes which AGI thresholds apply to which provisions.
- State income tax adjustments. State returns start from federal AGI but apply state-specific add-backs and subtractions. Each state has its own modification rules.
- AGI for estates and trusts. Form 1041 uses a different layout and a different income computation; this guide is Form 1040 only.
- AGI for nonresident aliens. Form 1040-NR has a different layout and applies different rules to many of the same income types.
- The detailed mechanics of Schedule C, Schedule E, Schedule D, or Schedule SE that feed into line 8. Each schedule is its own substantial topic; the Schedule SE explainer and quarterly estimated taxes guide cover the self-employment portion.
- The choice between standard deduction and Schedule A itemizing. See standard vs itemized deduction for the comparison.
For the AGI question specifically — what line is it on, how is it computed, what does it gate — the framework above is complete.
Sources
- IRS, the form itself with current-year instructions: About Form 1040.
- IRS, the supporting schedule for above-the-line adjustments and additional income: About Schedule 1 (Form 1040).
- IRS, the canonical definition used for e-filing identity verification: Definition of Adjusted Gross Income.
- IRS, the comprehensive plain-English guide to individual federal income tax that covers AGI mechanics in detail: Publication 17 — Your Federal Income Tax.
- IRS, the worksheet-driven definition of MAGI for Roth IRA contribution purposes, the MAGI most filers encounter: Amount of Roth IRA Contributions That You Can Make.
- IRS, the free transcript service that lets a filer verify AGI from a prior return against the IRS records: Get Transcript.
- IRS, the inflation adjustments behind the 2026 standard deduction, the student loan interest phase-out and the educator expense cap: Rev. Proc. 2025-32.
- IRS, the 2026 retirement plan limits behind the IRA deduction figures: Notice 2025-67.
Quick answers
On the 2025 Form 1040, do you subtract line 10 from line 9 to get AGI on line 11a?
Yes. On the 2025 Form 1040, line 11a (adjusted gross income) is line 9 (total income) minus line 10 (adjustments to income), and line 11b at the top of page 2 simply repeats the line 11a amount; on the 2024 form the same result sat on a single line 11. Line 10 is the single figure carried up from Schedule 1, line 26, which totals every above-the-line adjustment — the deductible half of self-employment tax, traditional IRA and HSA contributions, student loan interest up to $2,500, educator expenses, and the rest. So the arithmetic on the face of the form is literally line 9 − line 10 = line 11a (line 11 before 2025). This has held since the 2018 Tax Cuts and Jobs Act redesign of Form 1040, per the IRS definition of adjusted gross income.
What are the AGI and taxable income line numbers on Form 1040?
On the 2025 Form 1040, line 9 is total income, line 10 is adjustments to income (from Schedule 1, line 26), line 11a is adjusted gross income — line 9 minus line 10 — and line 11b carries that amount to page 2. Taxable income is further down: line 12e is the standard or itemized deduction, line 13a is the qualified business income deduction, line 13b is the additional deductions from Schedule 1-A, line 14 adds 12e, 13a and 13b, and line 15 (line 11b minus line 14) is taxable income, the figure the tax brackets are applied to. On the 2024 form the same path ran through lines 11, 12, 13, 14 and 15. AGI is line 11a (or 11); taxable income is line 15. They are never the same number unless your deductions are zero.
What line is AGI on Form 1040?
Adjusted gross income lands on Form 1040, line 11, for tax years 2018 through 2024, and on line 11a of the 2025 form, which repeats it on line 11b. The path to line 11 is mechanical: lines 1a–1z sum your wage and salary income from W-2 boxes plus a small set of related items; lines 2 through 8 add interest, dividends, IRA and pension distributions, Social Security, capital gains, and the catch-all "other income" totaled from Schedule 1 Part I; line 9 sums all of that into total income; line 10 subtracts the adjustments from Schedule 1 Part II; and line 11 is the result — AGI. The number on line 11 is the figure that downstream phase-outs, state returns, and identity-verification flows will reference for the rest of the year and into the next filing season.
What is the difference between gross income, AGI, and taxable income?
Gross income is everything you earned during the year before any subtractions — wages, interest, dividends, business income, capital gains, retirement distributions, the taxable portion of Social Security. AGI is gross income minus a specific statutory list of adjustments on Schedule 1 Part II — the deductible portion of self-employment tax, traditional IRA and HSA contributions (under certain conditions), student loan interest up to $2,500, educator expenses up to a small cap, and a handful of others. Taxable income is AGI minus either the standard deduction or itemized deductions on Schedule A, then minus the qualified business income deduction if applicable. Tax is then computed on taxable income — but AGI, not taxable income, is the figure most credit and deduction phase-outs actually test against.
Where on the 1040 is the AGI from last year used?
Your prior-year AGI from line 11 of last year's Form 1040 is used as an identity-verification anchor in two places during the current year's e-filing flow: IRS Free File and most commercial tax-prep software ask for it when you sign the return electronically (the "Self-Select PIN" method). If you filed last year, the AGI from that return is the answer. If you did not file last year, the answer is zero. The IRS does not accept estimated or rounded figures — the e-file system needs the exact line-11 number from the prior return, which is one reason to save a copy of every filed return.
Does Schedule 1 line 26 reduce AGI or taxable income?
Schedule 1 Part II concludes on line 26 with the total of all above-the-line adjustments — and that total is subtracted from Form 1040 line 9 (total income) to produce line 11 (AGI). So Schedule 1 line 26 reduces AGI directly. This is structurally more valuable than an itemized deduction on Schedule A, because reducing AGI also opens or preserves eligibility for credits and deductions whose phase-outs are keyed to AGI (Roth IRA contribution capacity, the Premium Tax Credit, the Saver's Credit, several education credits). A same-sized Schedule A itemized deduction reduces taxable income but does nothing for the AGI-tested phase-outs — which is why above-the-line adjustments are the planning lever that punches above its weight at the margin.
How do I calculate my AGI from my W-2?
Your W-2 does not show your AGI directly — Box 1 ("Wages, tips, other compensation") is the starting point, not the answer. Box 1 is already reduced by pre-tax 401(k), health-insurance, and payroll HSA contributions, so do not subtract those again. Add any taxable interest, dividends, capital gains, and other income from your 1099s to Box 1 to reach total income, then subtract any Schedule 1 Part II adjustments. The result is your AGI on Form 1040, line 11.
Educational content only. finbarrow is an independent editorial publication, not a licensed financial advisor, broker, tax preparer, or attorney. Verify rates and terms with the issuer or relevant regulator. See disclaimers and funding disclosures.